This article is general information about how insurers use AI. It is not insurance advice. For a decision about your own cover, check the policy wording or speak to a licensed adviser.
AI in insurance is software that reads documents, photos, and past claims, spots patterns in them, and helps people make faster decisions about quotes, claims, and fraud. It does the heavy reading and sorting. It does not replace the person who decides a disputed claim, explains a rejection, or takes responsibility for the outcome.
That split — machine sorts, human decides — is the whole story. Once you see it, the rest of insurance AI falls into place.
Key Takeaways
- AI in insurance mainly reads paperwork, scores risk, and sorts claims into simple, complex, or suspicious.
- A straightforward claim with clear photos can move much faster.
- AI can weigh far more pricing signals than a paper form, but a wrong signal can quietly charge some people more.
- A fraud flag is a suspicion, not a verdict.
- Insurers are now expected to explain, in plain language, when AI played a part in a decision about you.
What does AI actually do inside an insurance company?
It starts with paperwork. An insurer handles application forms, repair estimates, medical reports, photos, and years of old claim files, much of it arriving as scans or free-form text. Language models pull the key facts out of a document — the date, the damage, the cost — and computer vision does the same for photos, picking out a cracked headlight or a water-stained ceiling. It is reading, done at a speed no team could match.
The second job is scoring. A machine learning model studies thousands of past policies and claims, learns which combinations of factors tended to lead to expensive claims, and turns that into a score for each driver, house, or small business. Underwriters use the score as a starting point, not as the answer. Our complete guide to artificial intelligence explains the basics behind those scores.
The third job is sorting. When a claim lands, AI triages it in minutes: simple and well documented, complicated and needing a specialist, or unusual enough for a closer look.
| Task | What the AI does | What a person still does |
|---|---|---|
| Reading claim documents | Extracts dates, amounts, and damage details | Checks anything unclear and decides the claim |
| Pricing a policy | Scores risk from many signals at once | Sets the pricing rules and reviews odd cases |
| Spotting fraud | Flags patterns that look like past fraud | Investigates and decides whether fraud happened |
| Answering questions | Drafts replies and finds policy details fast | Handles complaints and explains decisions |
How does AI help with a claim?
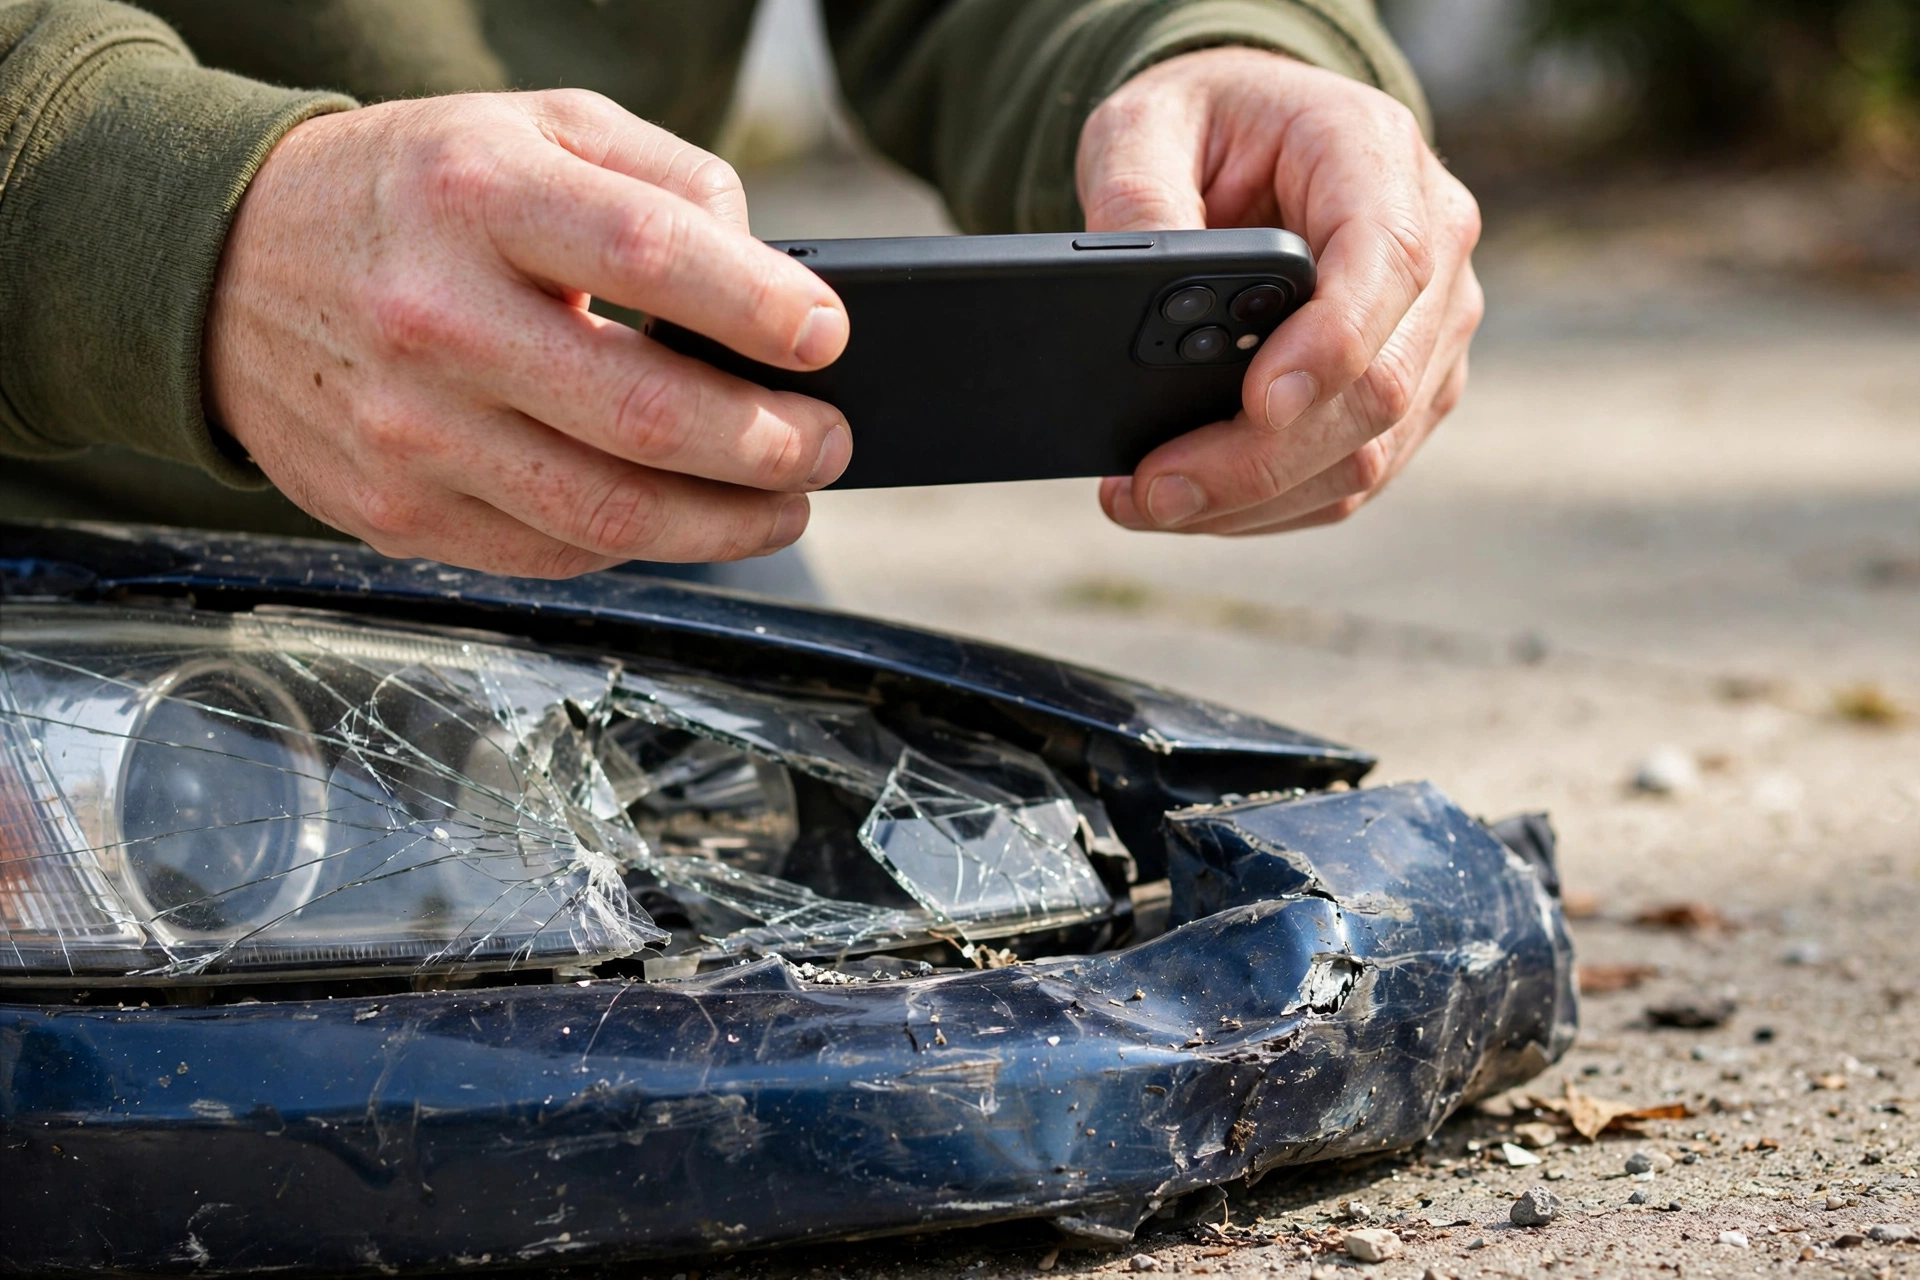
Take the most ordinary claim there is: you reverse into a bollard and dent your bumper. You open the insurer’s app and photograph the damage. The AI checks the photos — is the damage visible, does it match the description, is anything missing? It reads the policy to confirm what is covered and pulls up your claim history. If everything lines up and the repair cost sits below a threshold, the claim can be approved far sooner than the old paper process allowed.
But the AI did not decide your claim was honest, and it did not set the rules. It checked the case against rules people wrote. The moment something does not line up — a blurry photo, damage that looks older than the date given, an estimate far above the usual cost for that car — the case goes to a human adjuster. Our guide to how AI detects fraud looks at that pattern-spotting in more detail.
How does AI price a policy?
Pricing has always been a prediction: how likely is this person to claim, and how much might it cost? AI widens the lens. For car insurance, a model can weigh driving habits from a telematics device — smooth braking, little night-time mileage — alongside the car and where it is parked. For home insurance, it can add flood history for the street, the age of the roof, and local building costs.
That power is also the risk. A postcode can act as a stand-in for income or background if nobody checks, so a model leaning on the wrong signal can quietly charge some people more for reasons unrelated to how they drive or look after their home. That is why regulators in the United States, through the National Association of Insurance Commissioners, published principles saying AI in insurance should be fair, accountable, transparent, and safe. Our explainer on explainable AI covers why showing the reasoning behind a score matters so much here.
Where does AI spot fraud — and where can it get it wrong?
A single claim rarely looks suspicious on its own. Across thousands of claims, patterns emerge: the same phone number attached to several unrelated accidents, a repair shop whose bills always sit just below the threshold for manual review, or damage photos appearing in two different claims. AI finds those links because it never tires of cross-checking, comparing a new claim against years of history in seconds and ranking it by how closely it resembles past fraud.
But a high score is not proof. An honest customer can look unusual — a first claim after twenty claim-free years, a rare car with expensive parts, a crash on holiday. The flag leads to questions and a conversation, not an automatic rejection.
What does AI mean for customer service?
Most people meet insurance AI first as a chatbot. It answers routine questions at midnight: what does my policy cover, how do I add a driver, where is my claim up to? It pulls the answer from your policy documents instead of making you wait on hold. That works well for facts and badly for feelings — a person whose home has flooded wants someone who listens and takes ownership, not a cheerful bot. Good insurers use AI to clear simple questions away so staff have time for the calls that need a human. Our piece on AI in customer service looks at that handoff in more detail.
What should you check before you trust an AI-driven decision?
Ask four things. What did the AI actually decide — a recommendation a person reviewed, or an automatic outcome? What data went in, and can you correct it if it is wrong? Can you ask a person to look again, especially if a claim was reduced or refused? And is the explanation in plain language? Keep copies of what you send, with dates and names: when a claim is disputed, your own records are often what settles it.
Frequently Asked Questions
Does AI decide whether my insurance claim is paid?
Usually, no — not on its own. AI checks the documents and photos, scores the claim, and routes it. A person makes the final call, especially for large or disputed claims.
Can AI make my insurance cheaper?
It can. If the data shows you are a lower risk than the average for your group — careful driving, a well-maintained home — a model may price you better than a broad average would. But it can also work the other way, so compare quotes.
How do insurers use AI to detect fraud?
They compare each new claim with patterns from past claims, looking for links between people, vehicles, repair shops, and documents that would be hard to spot by hand. Suspicious patterns go to investigators. A flag alone is not proof of fraud.
Is it fair for AI to use my driving or home data to set a price?
It depends on the data and how it is checked. Rewarding careful driving is widely seen as fair. Using a factor that quietly stands in for income, health, or background is not, and regulators increasingly expect insurers to test for that.
Will AI replace insurance agents and adjusters?
For routine tasks, much of the work is already automated. For disputed claims, complex losses, and upset customers, people are still central, and regulators expect a human to be accountable. Expect fewer form-fillers and more specialists handling cases that need judgement.
The bottom line
AI in insurance is best understood as a very fast reader and sorter. It reads the documents, scores the risk, and puts the right cases in front of the right people sooner. Used well, that means quicker quotes, faster simple claims, and fraud caught before it is paid. Used badly — with unchecked data or no human review — it can quietly make unfair calls at scale.
Next time you buy or renew a policy, ask how the price was worked out and what would happen if you disagreed with a claim decision. An insurer that can answer both questions clearly is one that has kept a person in charge of its machines.
Further reading
- IBM on generative AI in underwriting and claims
- The NAIC principles for fair, accountable, transparent AI in insurance
- Our complete guide to artificial intelligence
- How AI detects fraud, and why a flag is only the start
- How AI helps with customer service, and when a human should take over
- Why AI needs to show its reasoning